Fully licensed & accredited
-
 Building & Plumbing Commission
-
 Australian Society of Building Consultants
-
 Strata Community Association
-
 Building Dispute Practitioners Society
This independent report is for Wollert owners with a damaged home and an insurance claim to support or dispute. It records what caused the damage, how far it extends and what the repair should include, with photographs and readings for each finding.
One of our inspectors will call you back.
If it is urgent, email [email protected]
Fully licensed & accredited
Building & Plumbing Commission Australian Society of Building Consultants Strata Community Association Building Dispute Practitioners Society Based on a non-destructive inspection, the report states what is damaged, the most likely cause and the extent. Where the workmanship of the original build is disputed, the report turns to the National Construction Code, the Building and Plumbing Commission's Guide to Standards and Tolerances, and the Australian Standards that govern the affected element.
21 checkpoints across 6 areas on a standard Wollert insurance building report. Anything we could not safely reach on the day is written up as a limitation rather than passed over.
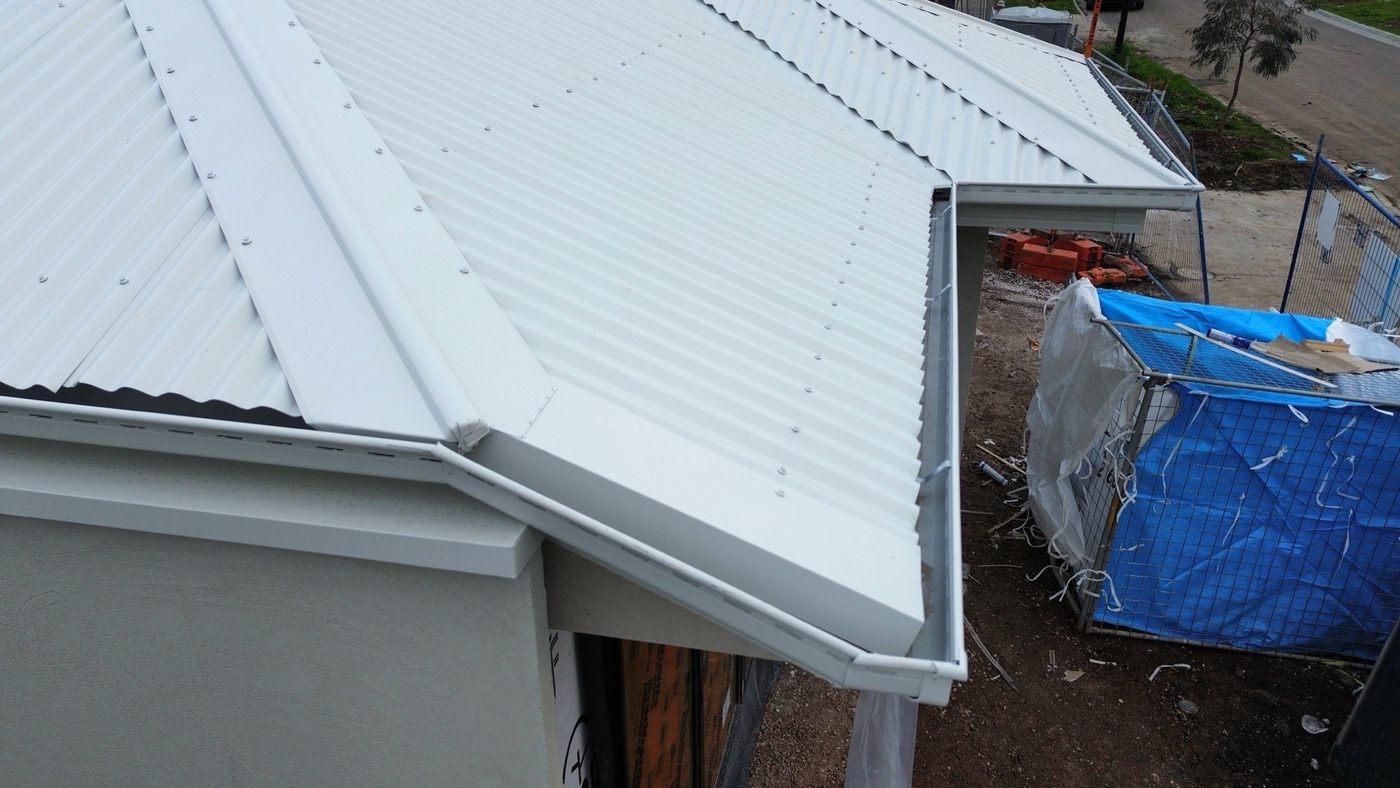
Examples from recent inspections around Wollert.
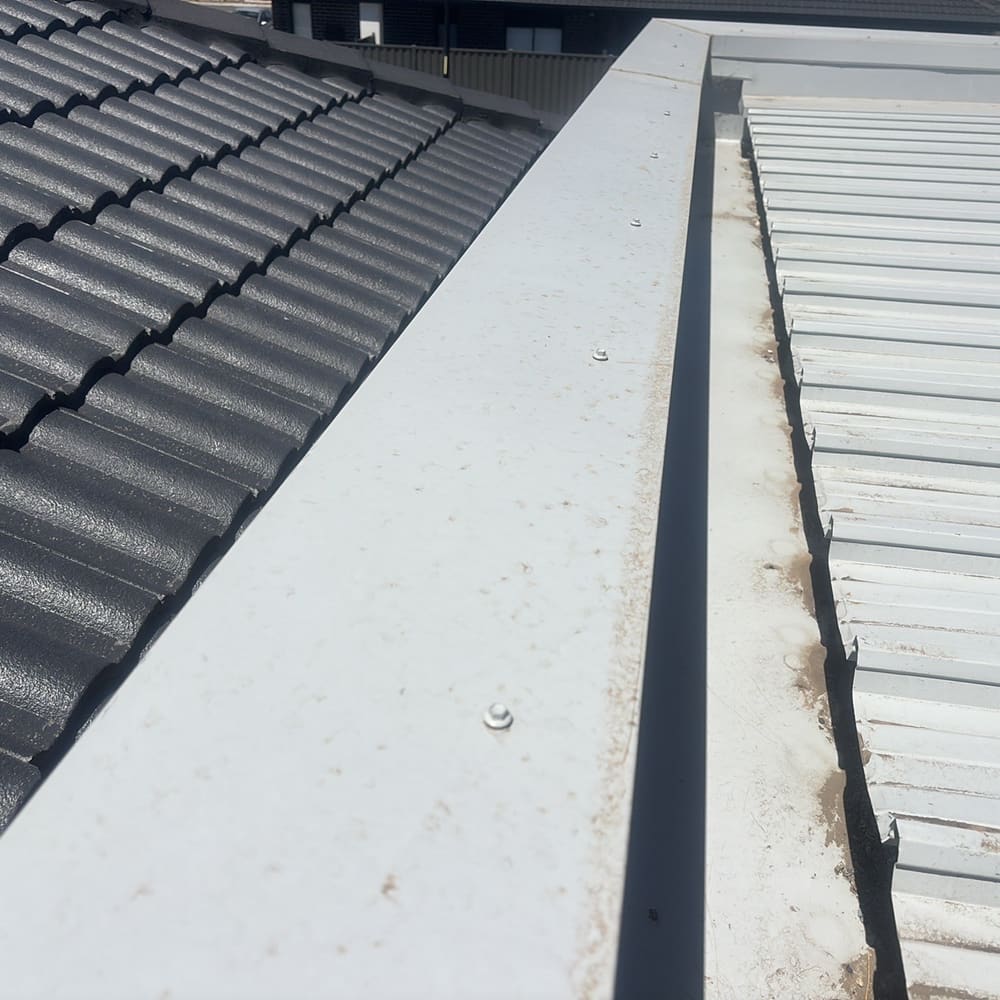
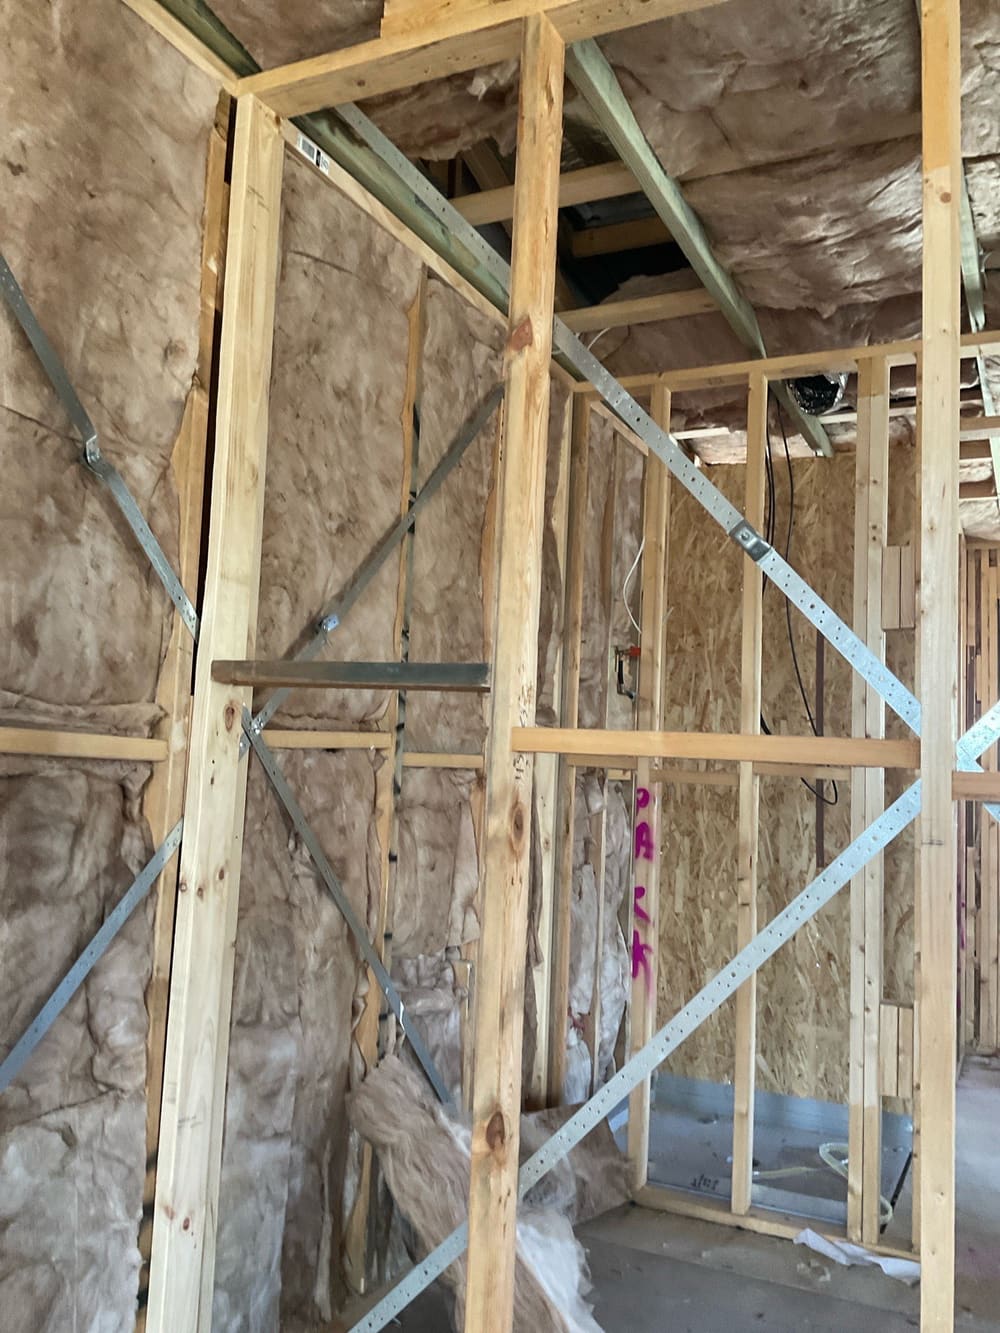
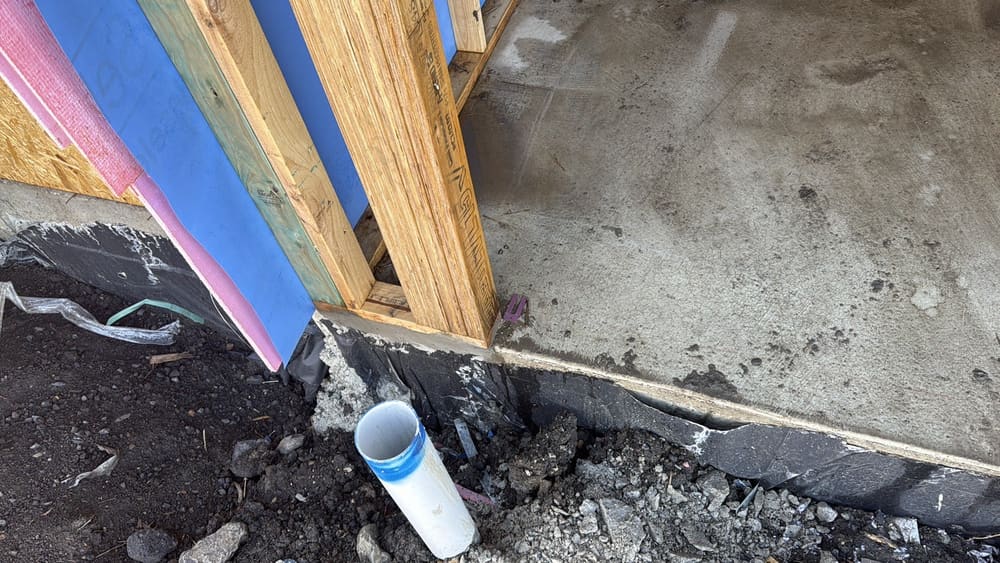
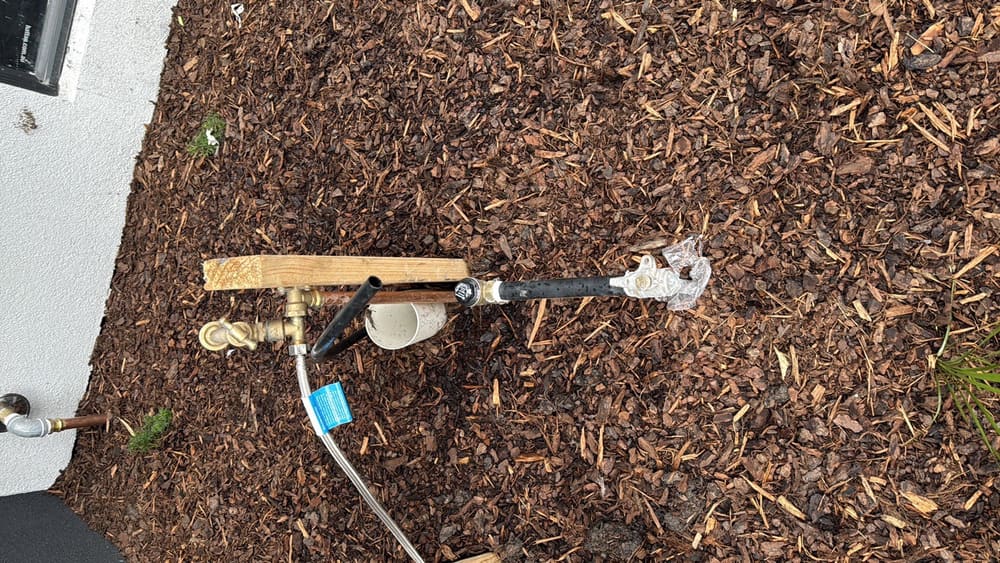
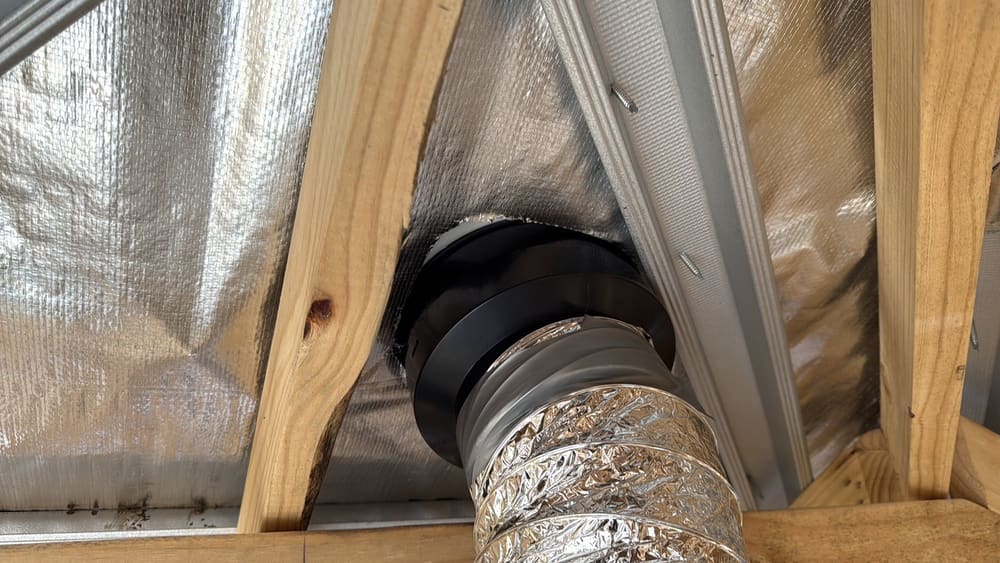
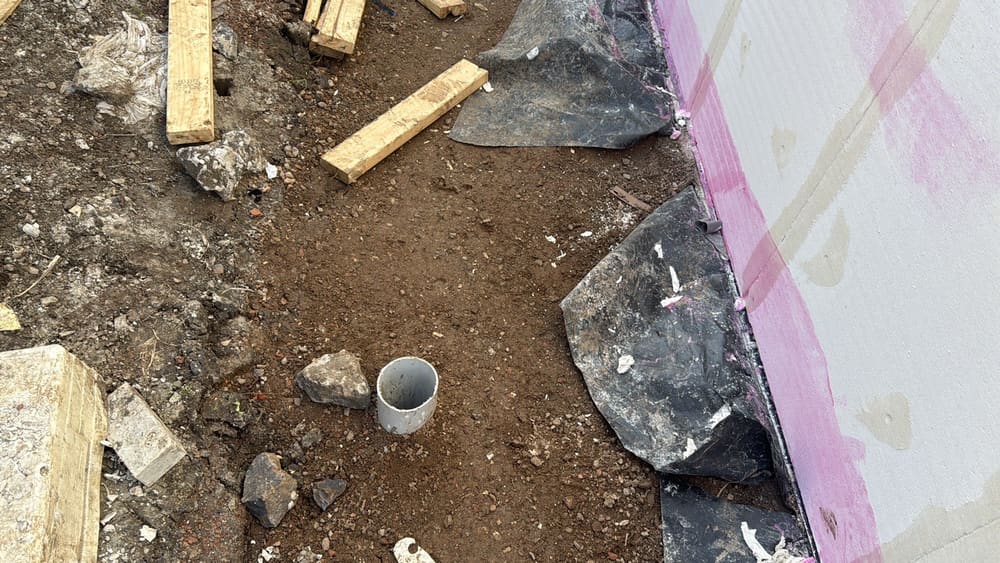
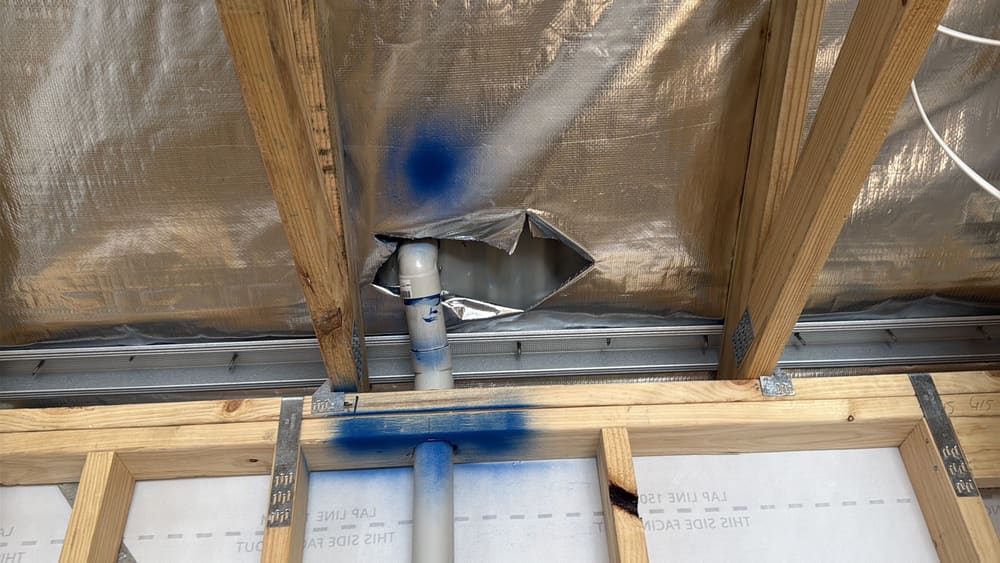
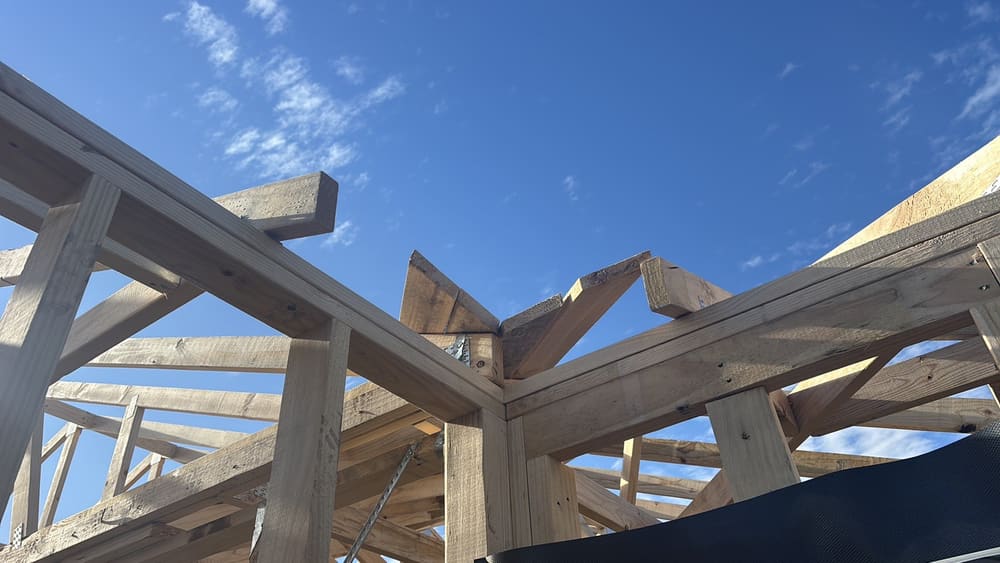
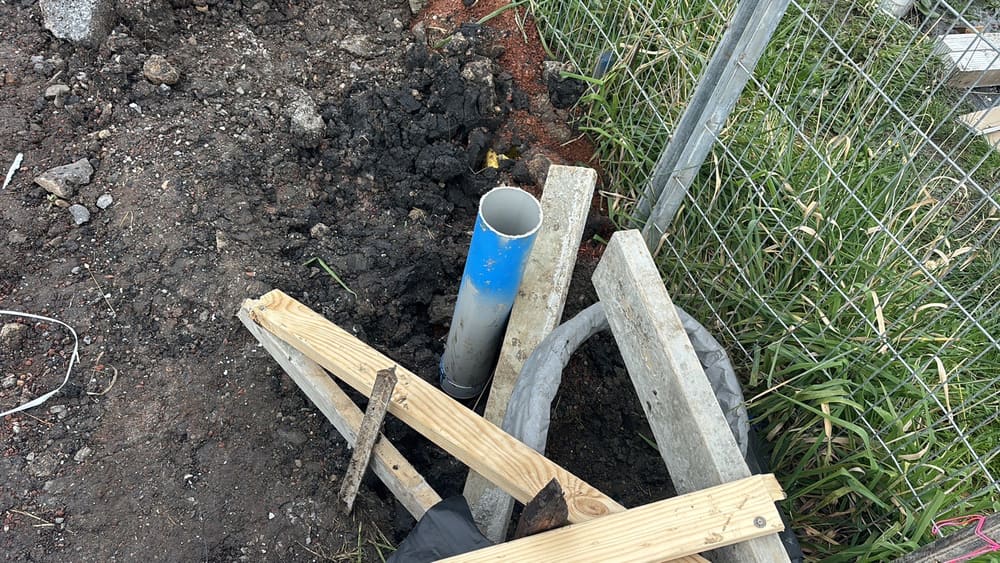
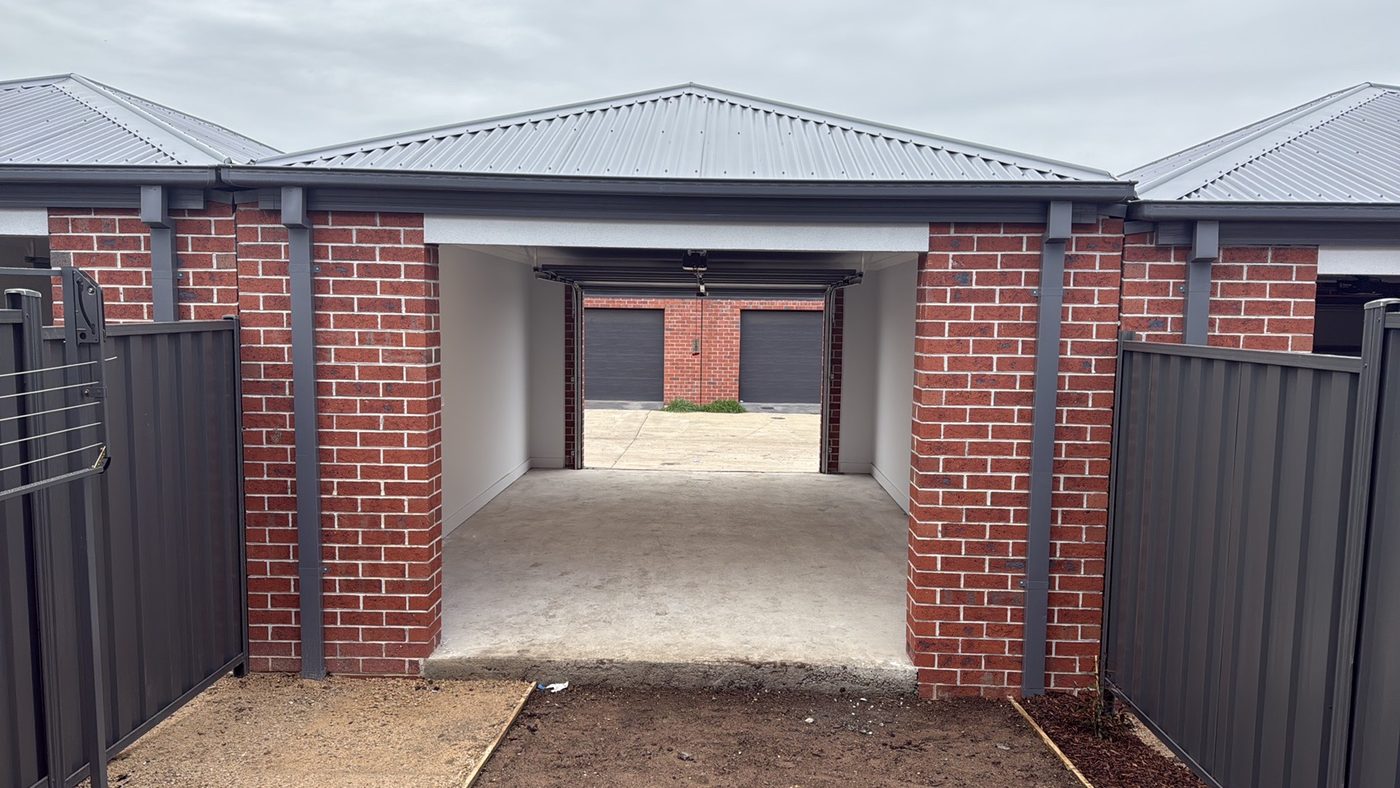
 New Construction Stage Inspections Seven separate inspections through the build, each timed to the last moment the work is still visible.
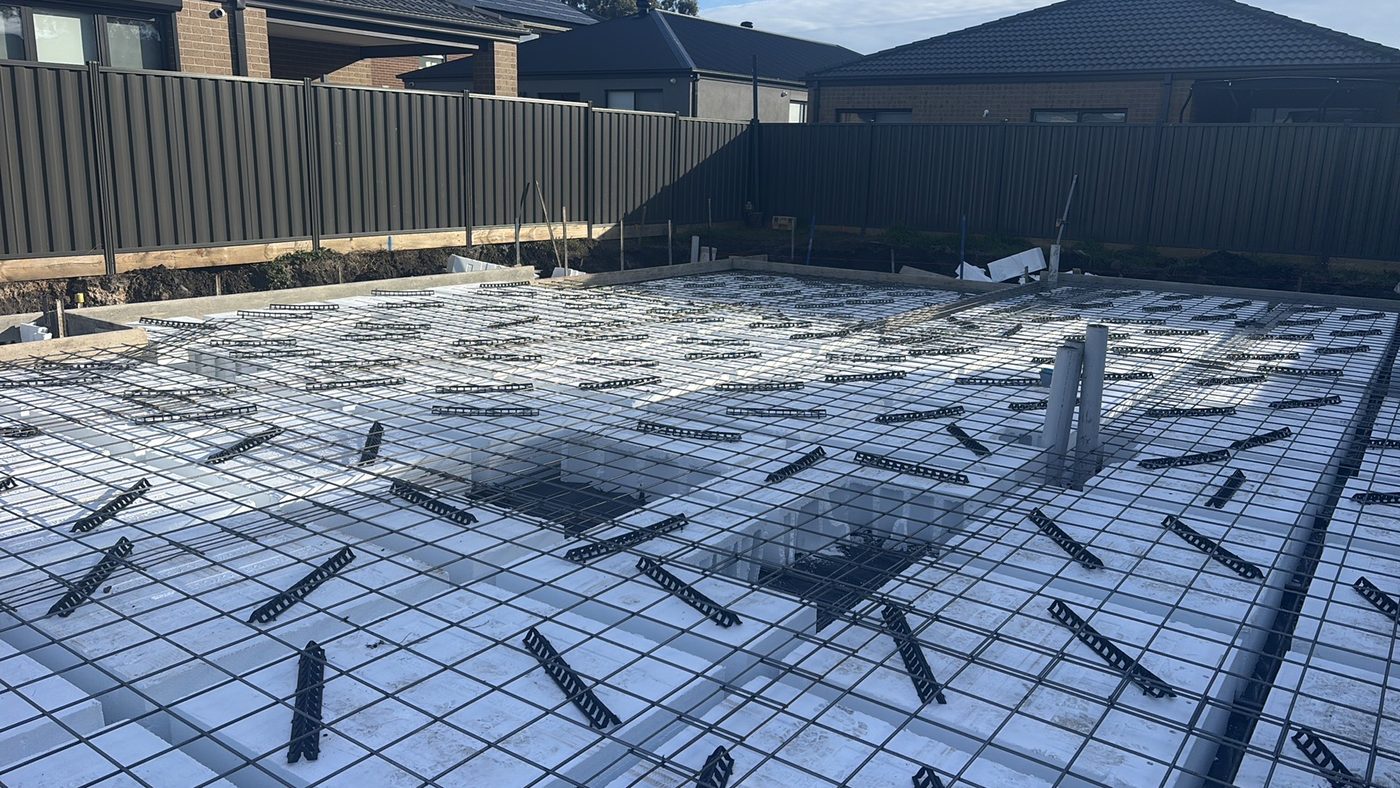
 Pre-Handover (PCI) Inspections The walk through before you accept keys, with every finish and completion item written down while you still have leverage.
 Building and Pest Inspections The building inspection and a timber pest inspection under AS 4349.3 in one attendance, with two reports that read against each other.
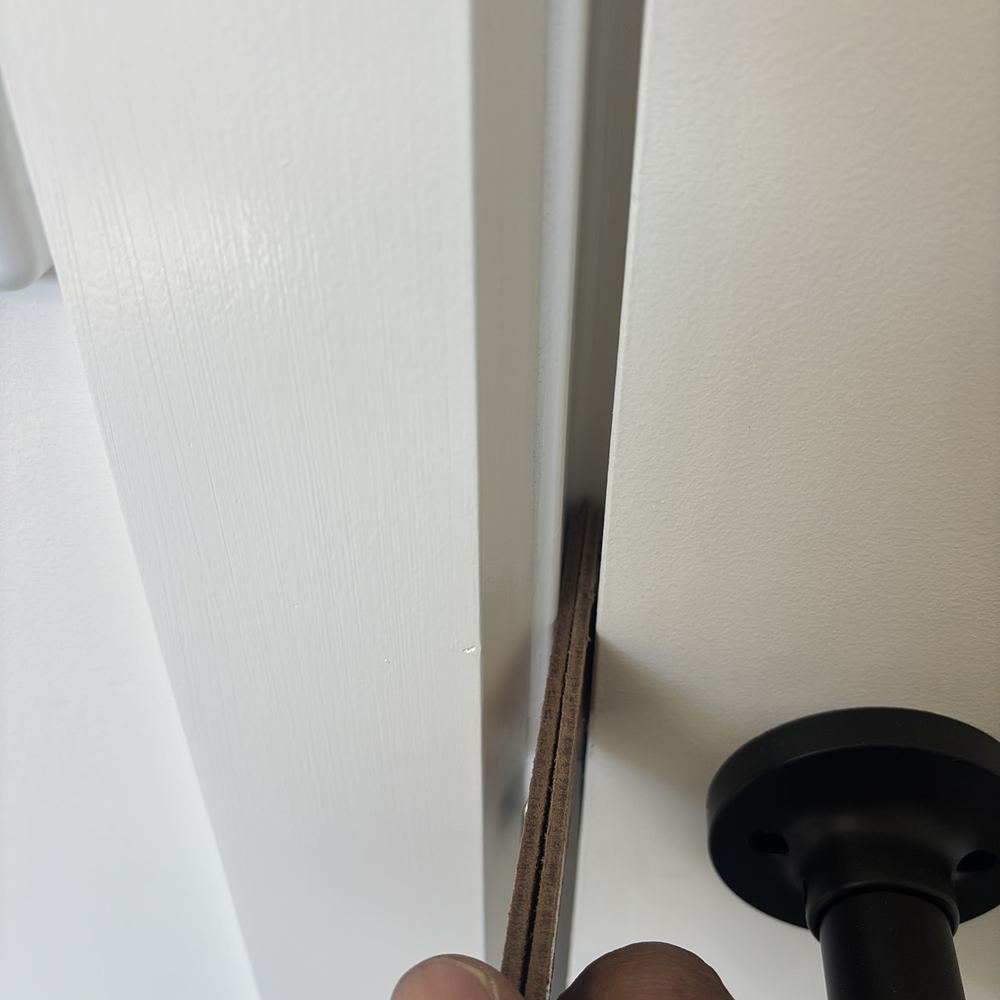
 VCAT Expert Witness Reports Defective or unfinished work in Wollert, reported as independent evidence for VCAT.
 Dilapidation Reports Photographic proof of your home's condition before the block next door is built.
 Pre-Sale Inspections Find the faults before a buyer's inspector does, and price the home accordingly.
 Mould Inspections Locate the moisture source behind the mould, not just the surface staining.
 Maintenance Inspections An annual check that catches small problems while they are still small.
 Apartment Pre-Settlement Your defect list before settlement on an off the plan apartment.
 Reinspections We return to confirm the builder actually fixed what the report listed.
 Timber Pest Inspections A standalone inspection under AS 4349.3 for evidence of termites and borers.
 Tax Depreciation Schedule Claim the depreciation on a Wollert investment property from day one. Commercial Property Inspections Condition and defect reporting for commercial and industrial buildings.
 Strata Reports What the owners corporation records say before you buy into a body corporate.
Instant online pricing for Wollert, or contact the booking team.
A written, independent account of the damage to your Wollert home: what is damaged, what most likely caused it, how far it extends and what repairs it needs. Findings are photographed and readings are taken wherever water or movement is involved. The report can support a claim, respond to a refusal or test the insurer's scope of works.
We read the crack itself, its width, its pattern and the signs of how long it has been open, along with floor levels and any doors or windows that bind. Because Wollert's basalt clay swells when wet and shrinks when dry, the report says plainly when cracking looks long-standing and when it looks recent, and it states what remains uncertain. Where an insurer relies on a wear and tear exclusion, it has to show the wear actually caused the loss, not just that wear is present.
No. A loss adjuster or assessor works for the insurer, which appoints them to assess the claim. We are engaged by you to report on the building and the report states the author's qualifications, but deciding claims, settling them and giving legal advice sit outside our role.
No, and no report can. The result depends on your policy wording, what caused the damage and the law. A clear account of cause and extent helps the people deciding, and if the matter goes to the Australian Financial Complaints Authority, it weighs the expert evidence from both sides.
When it denies a claim or pays only part, the General Insurance Code of Practice requires written notice of the parts of the claim it does not accept and the reasons. The notice must also say you can ask for the information and the expert or service supplier reports it relied on, and the Code says those reports are provided within 10 business days of a request. Our report then answers those reports point by point.
Because many home policies exclude faulty workmanship, the report first pins down what is leaking and why. If the original construction of a Wollert home is responsible, the Domestic Building Contracts Act 1995 implies warranties covering workmanship, reasonable care and skill, and suitable materials. Generally a building action has to start within 10 years of the occupancy permit being issued, or of the certificate of final inspection where there was no permit. The usual path is a written complaint to the builder and then the Building and Plumbing Commission's dispute resolution service, and advice on deadlines is worth getting without delay.
Yes. The scope is the insurer's list of funded repairs, and items can be absent because they are not covered or because they were missed on the day. We set it against what is on site and write our own rectification scope for a builder to quote from. Insurance Council guidance makes the same point to owners: a qualified builder or building consultant can give independent advice on the scope.
The cause and extent come from observation and measurement at the house. When the quality of the original construction is in question, we refer to the National Construction Code, the Building and Plumbing Commission's Guide to Standards and Tolerances in the edition in force when the home was built, and the matching Australian Standard, for instance AS 3740 for waterproofing in domestic wet areas.
It does not include opening walls, floors or ceilings, certifying engineering, soil or laboratory tests, plumbing pressure tests, electrical tests, mould sampling, contents or doing the repairs. Nor do we negotiate with the insurer or give legal advice. Where an opening or a plumber's test is needed to confirm the cause, the report explains where and why.
Use its internal complaints process first: the Code requires a decision within 30 calendar days, or an explanation of the delay together with your right to take it to AFCA. An unresolved complaint can then go to the Australian Financial Complaints Authority, a free and independent body whose decisions bind the insurer in the manner its rules describe. For most complaints, you must lodge within the earlier of six years from when you knew of the loss and two years after the insurer's final response.
Early, ideally before any repairs if the house is safe to leave as it is, because the signs of cause are clearest at the start. Tell us about any insurer or complaint deadline at booking. We inspect across Wollert, including Lyndarum North, Mason Quarter, Fellow, Northborne, Rathdowne and Wollert Rise, and in Epping North, Epping, Craigieburn, Donnybrook, Mernda, Doreen and Beveridge.